Does Homeowners Insurance Cover Hail-Damaged Windows?
Short answer: most homeowners policies list hail as a covered peril, so hail-damaged windows are often covered. How much the policy actually pays depends on your deductible, whether you have actual cash value or replacement cost coverage, and what the adjuster decides is storm damage rather than wear. Read your own policy and call your agent; nothing here replaces that.
Rapid City Window Pros is a free matching service, not a window company or an insurance adviser. We don't handle, negotiate or adjust claims. This guide explains the terms so you can ask better questions.
Does homeowners insurance cover hail damage to windows?
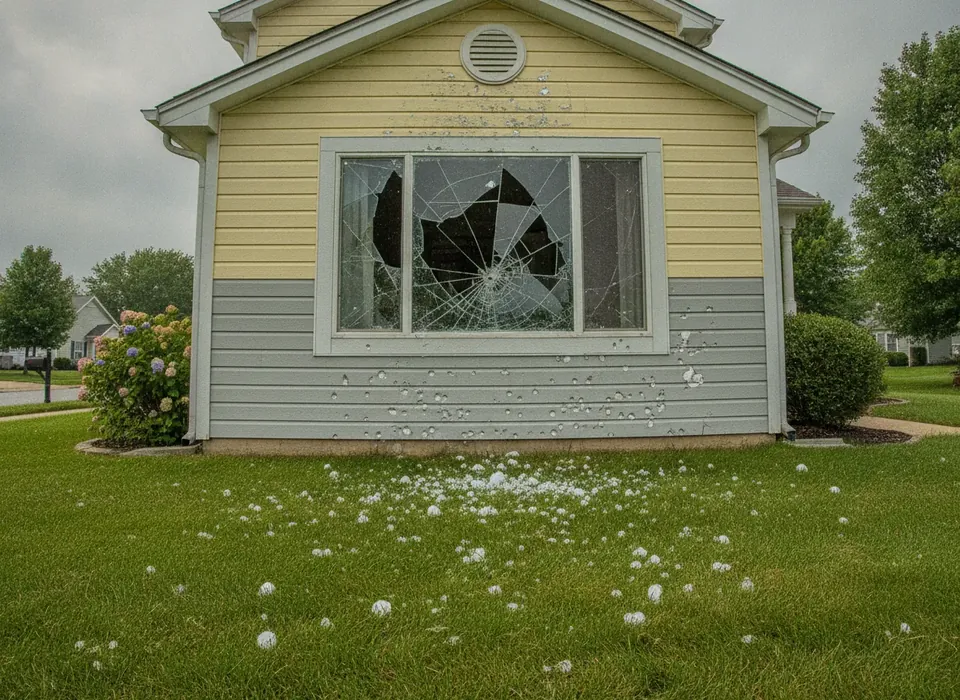
For sudden storm damage, usually yes, subject to your deductible and policy limits. Hail that cracks glass, dents frames or tears screens is the kind of sudden, accidental loss most standard homeowners policies are written for. What policies typically don't pay for is old age: a window that was already fogged, rotted or drafty before the storm doesn't become a covered loss because hail fell on it. That is why photos made right after the storm, and a written inspection, matter.
Some policies, especially those written in hail-prone areas, carry a separate wind/hail deductible or exclusions for cosmetic damage. Check the declarations page and any endorsements, not just the summary.
Actual cash value vs. replacement cost
This one line in your policy changes the check more than anything else.
| Actual cash value (ACV) | Replacement cost (RCV) | |
|---|---|---|
| What it pays | The cost to replace, minus depreciation for age and wear | The cost to replace with similar new windows |
| Older windows | Heavy depreciation can leave a small payment | Depreciation may be held back and paid once the work is done |
| What to ask your agent | How depreciation is figured for windows | Whether you must finish the work by a deadline to recover the held-back amount |
With more than half of Rapid City's homes built before 1980, a lot of windows here are 25 to 40 years old. On an ACV policy, depreciation on windows that age can be significant. Ask before you assume.
How the wind/hail deductible works
Many policies have a flat dollar deductible. Others use a separate wind/hail deductible, sometimes set as a percentage of the home's insured value instead of a flat amount. A percentage deductible can be much larger than people expect, so do the math with your own numbers. If the damage is a couple of cracked panes, the repair may cost less than the deductible, and a claim would pay nothing.
Should I file a claim for a few broken windows?
It depends on the numbers and your history. Things to weigh:
- Repair cost vs. deductible. Get a written repair or replacement quote first. If it is close to or below your deductible, a claim may not be worth it.
- Other damage. Hail that breaks windows often dents siding, gutters and the roof on the same side. The total may be well above your deductible even if the windows alone aren't.
- Claim history. A local agent interviewed by KOTA after the June 2026 west Rapid City storm noted that a claim you file but don't get paid on can stay on your record for about five years. Ask your agent how a claim may affect your premium or renewal.
- Reporting deadlines. Most policies require prompt notice. Calling your agent to ask questions is not the same as filing, so ask how they handle it.
What South Dakota law says about hail claims
- 30-day response. State law requires insurers to acknowledge and act on claim communications within 30 days, to explain denials promptly, and not to delay settling when liability is reasonably clear (SDCL 58-33-67).
- Deductible rebates. A contractor offering to pay, waive or rebate your deductible is illegal for residential roofing under SDCL 37-24-50, and contracts that do it are void. Treat the same offer from a window or siding company as a red flag.
- Door-to-door contracts. If you sign at home after a salesperson comes to you, South Dakota generally lets you cancel until midnight of the third business day (SDCL 37-24-5.1 and following).
- Your choice of contractor. As the local agent told KOTA, no insurer will dictate which contractor you use.
We found no South Dakota rule that requires insurers to replace undamaged windows so that everything matches. Don't sign anything that assumes the insurer will pay for matching windows on undamaged sides. Ask the adjuster how they will handle it.
Promises that should make you stop
- "Your insurance will pay for all new windows."
- "We'll take care of your deductible."
- "Sign this today so we can talk to your adjuster for you."
Only you, your insurer, and licensed public adjusters or attorneys you hire can negotiate your claim. The Attorney General's Consumer Protection line is 1-800-300-1986.
How window quotes fit into a hail claim
Adjusters write their own estimate. A written quote from a window company gives you something to compare it against, especially for things an adjuster can miss: split frames, bent cladding, damaged screens and hardware. Ask the installer to itemize the scope window by window, with photos. If the adjuster's estimate and the quote differ, share the quote with your insurer and ask them to explain the gap in writing.
Before anyone starts work, ask each installer for their South Dakota contractor's excise tax license number (verify it at 1-800-829-9188), proof of insurance, EPA Lead-Safe Certified Firm status if the house was built before 1978, and a City of Rapid City or Spearfish contractor license where required. South Dakota has no state window-contractor license, and we don't verify any of these for you.
For the practical side of the storm itself, read hail-damaged windows: what to do. The hail damage window replacement page covers how installers scope this work, and the window replacement cost guide has published price ranges. When you are ready, request free quotes from independent local installers.
Frequently asked questions
Does homeowners insurance cover hail-damaged windows?
Often yes, because most homeowners policies list hail as a covered peril. What you receive depends on your deductible, whether the policy pays actual cash value or replacement cost, and whether the adjuster sees storm damage rather than wear. Read your policy and call your agent.
What is the difference between ACV and replacement cost for windows?
Actual cash value pays the cost to replace minus depreciation, which can be large for older windows. Replacement cost pays to replace with similar new windows, though the insurer may hold back part of it until the work is finished.
Is it worth filing a hail claim for one or two windows?
Sometimes not. If the repair costs less than your deductible, a claim pays nothing, and a local agent told KOTA a filed claim can stay on your record for about five years. Get a written quote and check for other damage on the same side before deciding.
Will insurance replace all my windows so they match?
Don't assume it. We found no South Dakota rule requiring insurers to replace undamaged windows for matching. Ask your adjuster how they handle matching before you sign any contract.